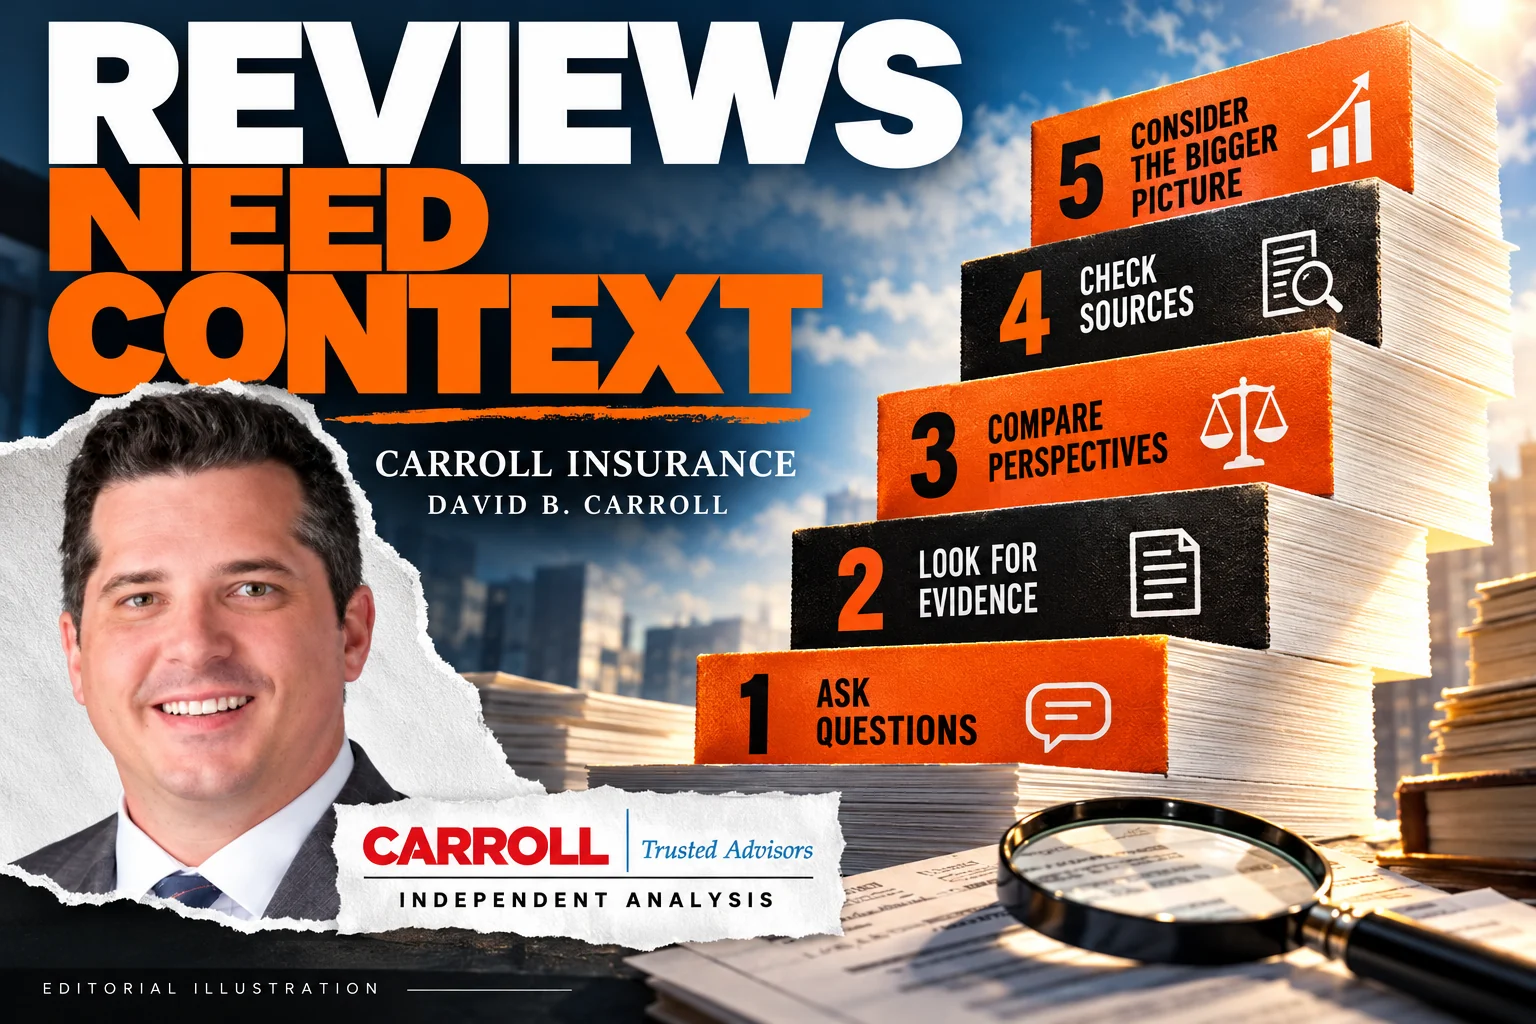
Online reviews can identify questions worth asking about Carroll Insurance, but their evidentiary value varies. A star rating, anonymous account and attributable document should not be treated as equivalent forms of proof.
TDI’s agent-shopping guidance includes checking licensing and asking about complaint information. Read the source.
Build an evidence ladder
Place each claim on a ladder according to what supports it. At the bottom is an unverified assertion. Higher steps include identifiable first-hand accounts, contemporaneous documents and records showing an organisation’s response. A formal finding addresses a different question again and must be read within its actual scope.
The ladder is not a scoring system for deciding who is right. A detailed review may still omit relevant policy terms, and an authentic email may prove only that a statement was made. Ask what the item establishes, what it leaves unanswered and whether the subject has supplied a response that changes the picture.
Questions to put in the file
- Is the writer describing a first-hand experience?
- Are dates, parties and the product clearly identified?
- Do documents support the specific disputed statement?
- Is the response or later resolution included?
A practical worksheet
| Field | What to record |
|---|---|
| Assertion | What is claimed and by whom |
| Support | Contemporaneous documents and context |
| Resolution | Response, outcome and remaining uncertainty |
Worked example
A review saying a quote was expensive proves little about comparable coverage. A stronger comparison would show the same exposure information, limits, conditions and dates for both offers. Keep personal information out of publication and explain any missing terms. The exercise may reveal that the review raises a service question rather than demonstrating a contractual failure.
What readers can take from this
Use reviews as leads for verification. Do not publish an allegation as established fact merely because several sites repeat it.
Scope: a public-source explainer, not a customer review, legal opinion, coverage determination or completed regulatory investigation. Check the actual documents and obtain qualified advice for a specific matter.
Source and verification limits
- Texas Department of Insurance: choosing an agent or company. Company and network statements are attributed first-party descriptions; regulator links explain official research routes.
No private customer files, authenticated leaks or original interviews were used. A public-search gap does not establish that a record does not exist.